Hyperion DeFi Schedules Fourth Quarter and Full Year 2025 Earnings Call for Thursday, March 26 at 8:00 a.m. ET

Hyperion DeFi Schedules Fourth Quarter and Full Year 2025 Earnings Call for Thursday, March 26 at 8:00 a.m. ET


Hyperion DeFi Schedules Fourth Quarter and Full Year 2025 Earnings Call for Thursday, March 26 at 8:00 a.m. ET

LAGUNA HILLS, Calif., March 17, 2026 (GLOBE NEWSWIRE) — Hyperion DeFi, Inc. (NASDAQ: HYPD) (“Hyperion DeFi” or the “Company”), the first U.S. publicly listed company building a long-term strategic treasury of Hyperliquid’s native token, HYPE, today announced that it will hold its earnings conference call and webcast for the fourth quarter and full year ended December 31, 2025, on Thursday, March 26, 2026 at 8:00 a.m. Eastern Time.

A press release detailing these results will be issued prior to the call on the same day.

Conference Call Information

To participate in this event, please log on or dial in approximately 5 minutes before the beginning of the call.

Date: March 26, 2026
Time: 8:00 a.m. ET
Access ID: 13758512
Webcast: https://viavid.webcasts.com/starthere.jsp?ei=1751342&tp_key=ef0e483a89
Dial in: 1-877-407-9039 or 1-201-689-8470
Call me™: https://callme.viavid.com/viavid/?callme=true&passcode=13754799&h=true&info=company-email&r=true&B=6

Participants can use the dial-in numbers listed above or click the Call me™ link for instant telephone access to the event. The Call me™ link will be available 15 minutes prior to the scheduled start time.

Replay Information

Dial-In: 1-844-512-2921 or 1-412-317-6671
Replay Expiration: Thursday, April 9, 2026
Access ID: 13758512

About the Hyperliquid Platform and the HYPE Token

Hyperliquid is a next-generation layer one blockchain optimized for high frequency, transparent trading. The blockchain includes fully on-chain perpetual futures and spot order books, with every order, cancel, trade, and liquidation occurring within 70 millisecond block times. It also hosts the HyperEVM, a general-purpose smart contract platform that supports permissionless decentralized financial applications akin to Ethereum.

HYPE is the native token of Hyperliquid. Staked HYPE provides utility for users via reduced trading fees and increased referral bonuses. As of March 2026, more than 41 million HYPE have been autonomously purchased and sequestered by the blockchain with the trading fees generated on the network’s central limit order books.

About Hyperion DeFi, Inc.

Hyperion DeFi, Inc. is the first U.S. publicly listed DeFi company building on Hyperliquid. The Company provides investors with streamlined access to the Hyperliquid ecosystem, one of the fastest growing, highest revenue-generating blockchains in the world. Shareholders benefit from compounding exposure to HYPE, both from its native staking yield and additional revenues generated from its unique on-chain utility.

Hyperion DeFi is also developing its proprietary Optejet User Filled Device that is designed to work with a variety of topical ophthalmic liquids, including artificial tears and lens rewetting products. The Optejet is especially useful in chronic front-of-the-eye diseases due to its ease of use, enhanced safety and tolerability, and potential for superior compliance versus standard eye drops. Together, these benefits may result in higher treatment compliance and better outcomes for patients and providers.

For more information, please visit Hyperiondefi.com or follow @hyperiondefi on X.

Forward Looking Statements

Except for historical information, all the statements, expectations and assumptions contained in this press release are forward-looking statements. Forward-looking statements include, but are not limited to, statements that express our intentions, beliefs, expectations, strategies, predictions or any other statements, our future activities or other future events or conditions, including the viability of, and risks associated with, our cryptocurrency treasury strategy, the growth and revenue potential of the Hyperliquid ecosystem and the growth prospects of the Company. These statements are based on current expectations, estimates and projections about our business based, in part, on assumptions made by management. These statements are not guarantees of future performance and involve risks, uncertainties and assumptions that are difficult to predict. Therefore, actual outcomes and results may, and in some cases are likely to, differ materially from what is expressed or forecasted in the forward-looking statements due to numerous factors discussed from time to time in documents which we file with the U.S. Securities and Exchange Commission.

Any forward-looking statements speak only as of the date on which they are made, and except as may be required under applicable securities laws, Hyperion DeFi does not undertake any obligation to update any forward-looking statements.

Certain information contained in this press release relates to or is based on studies, publications, surveys and other data obtained from third-party sources and Hyperion DeFi’s own internal estimates and research. While Hyperion DeFi believes these third-party studies, publications, surveys and other data to be reliable as of the date of this press release, it has not independently verified, and makes no representation as to the adequacy, fairness, accuracy or completeness of, any information obtained from third-party sources. In addition, no independent source has evaluated the reasonableness or accuracy of Hyperion DeFi’s internal estimates or research and no reliance should be made on any information or statements made in this press release relating to or based on such internal estimates and research. You should conduct your own investigation and analysis of Hyperion DeFi, its business, prospects, results of operations and financial condition. In furnishing this information, Hyperion DeFi does not undertake any obligation to provide you with access to any additional information (including forward-looking information and any projections contained herein) or to update or correct the information.

Hyperion DeFi, Inc. Investor Contact:
Jason Assad
Hyperion DeFi, Inc.
IR@hyperiondefi.com
(678) 570-6791

Recent Study Confirms Fundamental Correlation Between Severity of Obstructive Sleep Apnea and Oral Anatomy

Recent Study Confirms Fundamental Correlation Between Severity of Obstructive Sleep Apnea and Oral Anatomy


Recent Study Confirms Fundamental Correlation Between Severity of Obstructive Sleep Apnea and Oral Anatomy

Vivos CARE Oral Medical Devices Proven to Enhance Airways by Redeveloping Dental Arch Forms and Jaws

LITTLETON, Colo., March 17, 2026 (GLOBE NEWSWIRE) — Vivos Therapeutics, Inc. (“Vivos” or the “Company’’) (NASDAQ: VVOS), a leading medical device and healthcare services company focused on the treatment of breathing related sleep disorders and associated chronic health conditions, today announced that an a recent study published in the Journal of Clinical Medicine supports Vivos’ long maintained belief that dental and facial morphology characterized by narrow palatal (upper) dental arches, high peaked palates, and recessed lower jaws were directly correlated to the prevalence and severity of obstructive sleep apnea (OSA) in adults and children.

Over the past decade, Vivos-trained providers have successfully treated tens of thousands of OSA patients using Vivos CARE devices to redevelop and enhance airways.   Vivos CARE devices have been cleared by the U.S. Food and Drug Administration (FDA) for adult patients diagnosed with mild, moderate and severe OSA and moderate-to-severe OSA in children ages 6 to 17. Many Vivos patients finish treatment in less than 12 months with little or no remaining OSA symptoms. Thus, in the majority of such Vivos patients, there is no need for nightly lifetime intervention with CPAP, traditional oral appliances, or neurostimulation implants.

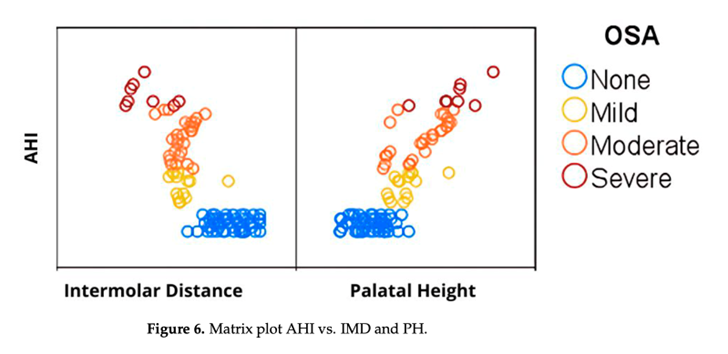
The recent study, the “Correlation Between Severity of Obstructive Sleep Apnea and Dental Arch Form in Adults,” first published in October 2025, affirms what the over 2,000 Vivos-trained providers see every day in clinical practice—that very small changes in the size, shape, and position of the dentition and jaws evoke significant changes in the form, function and patency of the human airway. The study conclusions indicate that maxillary morphology is associated with OSA severity, narrower intermolar distance (IMD) and greater palatal height (PH) linked to higher Apnea-Hypopnea Index (AHI). Larger airways are less prone to collapse (apnea / hypopnea events) during sleep. Fewer apnea / hypopnea events often means less sleep disruption, less blood oxygen desaturation (hypoxia) and better overall sleep architecture.

One hundred patients participated in the study, with 50 OSA patients and 50 controls. The OSA group exhibited significantly narrower transverse intermolar distance and higher palatal height compared to the control group. Linear regression analysis demonstrated a strong association (p<0.001) between these two key craniofacial parameters and OSA severity, as measured by the industry standard measure AHI. These results held true across all demographics. The figure below reflects the strong anatomical correlations in the study.

Matrix plot AHI vs. IMD and PH.

After years of research and product development, in November 2024 the FDA granted Vivos CARE devices an unprecedented 510(k) clearance to treat severe OSA patients. No other oral appliance had ever received such a clearance, nor has any similar clearance been granted since. Moreover, the mechanism of action in Vivos CARE devices is unique and capable of creating what are believed to be lasting results by gradually redeveloping and repositioning the dental arches and jaws.     

Kirk Huntsman, CEO of Vivos Therapeutics, said, “This study reaffirms our longstanding view that cranial and oral morphology is directly correlated to not only the presence of OSA, but also its severity. Traditional treatments such as CPAP, mandibular advancement oral appliances, and neurostimulation implants, all act to temporarily manage symptoms, but require repeated nightly use over a lifetime to remain effective. Vivos CARE devices rehabilitate and restore optimal airway size and shape, allowing patients to breathe more fully and sleep more deeply. After nearly 50 years of limited and undesirable treatment options, patients now have a real choice that is both safe and effective.”

“This year, we estimate that several million Americans will undergo a sleep test. In our experience, nearly half of them will test positive for OSA. Those patients will need to make a serious and life-changing decision—what they will do about their serious medical condition. OSA doesn’t go away on its own, and it will likely get worse with time. If left untreated, it will affect their cardiovascular system, their neurocognitive abilities, their risk of diabetes, chronic fatigue, mental health and more. Yet over 90% will still receive a medical prescription for CPAP, the “Gold Standard” treatment that, statistically, will soon be abandoned by over half of those patients. Then what? That’s why we’re seeing more and more such OSA patients turning to Vivos devices for OSA treatment,” concluded Mr. Huntsman.

About Vivos Therapeutics, Inc.

Vivos Therapeutics, Inc. (NASDAQ: VVOS) is a medical technology company focused on developing and commercializing innovative diagnostic and treatment methods for patients suffering from breathing and sleep issues arising from certain dentofacial abnormalities such as obstructive sleep apnea (OSA) and snoring in adults. Vivos’ devices have been cleared by the U.S. Food and Drug Administration (FDA) for adult patients diagnosed with all severity levels of OSA and moderate-to-severe OSA in children ages 6 to 17. Vivos’ groundbreaking Complete Airway Repositioning and Expansion (CARE) devices are the only FDA 510(k) cleared technology for treating severe OSA in adults and the first to receive clearance for treating moderate to severe OSA in children. 

OSA affects over 1 billion people worldwide, yet 80% or more remain undiagnosed and unaware of their condition. This chronic disorder is not just a sleep issue—it is closely linked to many serious chronic health conditions. While the medical community has made strides in treating sleep disorders, breathing and sleep health remain areas that are still not fully understood. As a result, legacy OSA treatments like CPAP are often mechanistic and fail to address the root causes of OSA. 

Founded in 2016 and based in Littleton, Colorado, Vivos is working to change this. Through innovative technology, education, and acquisitions of, or commercial collaborations with, sleep healthcare providers, Vivos is empowering healthcare providers to address the complex needs of OSA patients more thoroughly.

Vivos calls the use of its appliances and protocols to treat OSA The Vivos Method, which offers a proprietary, clinically effective solution that is nonsurgical, noninvasive, and nonpharmaceutical, providing hope to allow patients to Breathe New Life.

For more information, visit www.vivos.com. 

Cautionary Note Regarding Forward-Looking Statements

This press release, including statements of the Company’s management and other parties made in connection therewith, contain “forward-looking statements” (as defined in Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended) concerning future events. Words such as “may”, “would”, “should”, “expects”, “projects,” “potential,” “intends”, “plans”, “believes”, “anticipates”, “hopes”, “estimates”, “goal”. “aim” and variations of such words and similar expressions are intended to identify forward-looking statements. In this press release, forward-looking statements include, without limitation, those relating to the actual future impact on Vivos’ revenue and profitability from its operations or the benefits to Vivos of the study as described herein. These statements involve significant known and unknown risks and are based upon several assumptions and estimates, which are inherently subject to significant uncertainties and contingencies, many of which are beyond Vivos’ control. Actual results (including the actual results from the study and individual results of OSA treatment) may differ materially and adversely from those expressed or implied by such forward-looking statements. Factors that could cause actual results to differ materially include, but are not limited to: (i) the risk that Vivos may be unable to effectively market or continue to integrate business from the acquisition and alliance model into its own or otherwise implement sales, marketing and other strategies that increase revenues, (ii) the risk that some patients may not achieve the desired results from using Vivos’ products, (iii) risks associated with regulatory scrutiny of and adverse publicity in the sleep apnea diagnosis and treatment sector; (iv) the risk that Vivos may be unable to secure additional financing to continue operations, acquire additional sleep centers practices on reasonable terms, or maintain its Nasdaq listing when needed, if at all, (v) market and other conditions that could impact Vivos’ business or ability to obtain financing, and (vi) other risk factors described in Vivos’ filings with the Securities and Exchange Commission (“SEC”). Vivos’ filings can be obtained free of charge on the SEC’s website at www.sec.gov. Except to the extent required by law, Vivos expressly disclaims any obligations or undertaking to release publicly any updates or revisions to any forward-looking statements contained herein to reflect any change in Vivos’ expectations with respect thereto or any change in events, conditions, or circumstances on which any statement is based.

Media Inquiries: 

Jennifer Hauser, Executive Assistant to the CEO

Investor Relations Contact
investors@vivoslife.com

A photo accompanying this announcement is available at https://www.globenewswire.com/NewsRoom/AttachmentNg/2bbc6139-7151-4edd-89dd-5253307b498b

Axe Compute Appoints Two Technology and Telecom Luminaries to Board of Directors as Company Accelerates AI Infrastructure Strategy

Axe Compute Appoints Two Technology and Telecom Luminaries to Board of Directors as Company Accelerates AI Infrastructure Strategy


Axe Compute Appoints Two Technology and Telecom Luminaries to Board of Directors as Company Accelerates AI Infrastructure Strategy

Theodore Zhu, Ph.D. and Thorsten Dirks Bring Deep Semiconductor, Telecom, and International Transformation Expertise

NEW YORK, March 17, 2026 (GLOBE NEWSWIRE) — Axe Compute (NASDAQ: AGPU), the enterprise GPU infrastructure company giving enterprises and entrepreneurs unparalleled choice and access to AI compute, today announced the appointment of Theodore Zhu, Ph.D. and Thorsten Dirks to its Board of Directors, effective March 12, 2026. The appointments mark a significant step in Axe Compute’s strategic pivot to become the definitive enterprise GPU-as-a-Service platform for the global AI era.

Together, Zhu and Dirks bring more than four decades of combined experience spanning semiconductor innovation, large-scale telecommunications transformation, international M&A, and enterprise digitalization — precisely the depth required as Axe Compute scales GPU networks to serve the growing demands of enterprise AI workloads worldwide.

“We’re excited to add these industry experts to our board as Axe Compute grows our compute business. Theodore and Thorsten don’t just bring credentials — they bring the judgment that comes from building technology businesses through real market disruption. Both are an addition to the board that matches our ambition to be the leader in the GPU Infrastructure space.”
— Chris Miglino, Chief Executive Officer, Axe Compute

Theodore Zhu, Ph.D. — Board Director

Theodore Zhu, Ph.D. is a seasoned semiconductor innovator and technology executive whose career sits at the intersection of advanced hardware design and enterprise commercialisation. He is the Founder and Chairman of Iotelligent Technology, which he established in 2011, and previously served as President and Chief Operating Officer of Celestial Semiconductor. He is also co-founder of Jazz Semiconductor. Zhu holds a Ph.D. in Solid State Physics and is the author and holder of more than 85 U.S. patents — a record that speaks to both the depth of his technical expertise and his ability to translate research into commercially viable technology.

“Axe Compute has a structural advantage that is rare in this market — global reach, minimal CapEx, and enterprise-grade reliability. I’m delighted to join the board at this pivotal moment.”
— Theodore Zhu, Ph.D., Board Director, Axe Compute

Thorsten Dirks — Board Director

Thorsten Dirks is one of Europe’s most accomplished technology executives, with approximately 19 years of board experience and 15 years as a chief executive officer across some of the continent’s largest and most complex technology and telecommunications organisations. He has served as CEO of E-Plus Group, Telefónica Deutschland, and Deutsche Glasfaser, and has served as an Executive Board Member at both Deutsche Lufthansa and KPN. His expertise in large-scale transformation, M&A, post-merger integration, and enterprise digitalization is a direct asset as Axe Compute expands its global footprint and deepens its enterprise client relationships.

“The companies that win are the ones that remove friction before their competitors admit it’s a problem. Axe Compute has identified a real friction point in enterprise AI infrastructure and built a sound model to solve it. The global opportunity here is significant.”
— Thorsten Dirks, Board Director, Axe Compute

Strategic Context

The board additions come as Axe Compute sharpens its focus on the enterprise AI infrastructure market — a sector facing acute supply constraints, geographic gaps in hyperscaler coverage, and a structural mismatch between enterprise AI demand and available compute capacity. Axe Compute’s model — delivering GPU access across 200+ global locations through its partnership with Aethir’s distributed network, with zero capital expenditure per revenue dollar and 48-hour deployment timelines — is designed to address these constraints directly.

Zhu’s semiconductor expertise reinforces Axe Compute’s technical credibility with enterprise buyers and investors evaluating the company’s GPU infrastructure capabilities. Dirks’ international operating experience positions the company to accelerate expansion into EMEA and APAC markets — regions where hyperscaler coverage remains limited and enterprise AI demand is growing rapidly.

About Axe Compute

Axe Compute (NASDAQ: AGPU) is redefining AI compute infrastructure by giving enterprises and entrepreneurs greater choice in GPU infrastructure. Through a globally distributed network spanning more than 200 locations, Axe Compute’s platform is designed to enable enterprise-grade AI compute deployments in as little as 48 hours, with no data egress or bandwidth charges and infrastructure that gives customers the option to avoid vendor lock-in — all at competitive market rates. Axe Compute is among the first U.S. publicly traded companies focused on building globally distributed AI compute infrastructure.

Media Contact

Axe Compute Communications
erin@axecompute.com
axecompute.com | NASDAQ: AGPU

Forward-Looking Statements: This press release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements involve known and unknown risks, uncertainties, and other factors that could cause actual results to differ materially from those expressed or implied. Axe Compute undertakes no obligation to update these statements.

Cantourage Group SE publishes preliminary figures for 2025 – Revenue rises to EUR 92.8 million

Cantourage Group SE

/ Key word(s): Annual Results/Preliminary Results

Cantourage Group SE publishes preliminary figures for 2025 – Revenue rises to EUR 92.8 million

17.03.2026 / 10:04 CET/CEST

The issuer is solely responsible for the content of this announcement.


  • Significant growth in revenue and earnings
  • International expansion sustainably contributes to positive business development
  • Focus on premium products – increasing price competition in the German low-price segment

Cantourage Group SE (ISIN: DE000A3DSV01) today published preliminary consolidated figures for the 2025 financial year. During the reporting period, the company achieved a significant increase in both revenue and earnings, thereby continuing its dynamic growth trajectory as one of the leading European companies in the field of medical cannabis.

Group revenue increased to EUR 92.8 million in the 2025 financial year (previous year: EUR 50.9 million), representing growth of 82.3% compared to the previous year. Preliminary EBITDA rose to EUR 5.7 million (previous year: EUR 3.8 million).

International expansion supports sustainable earnings quality

Strategic expansion into selected core European markets is increasingly contributing to improved revenue and earnings. Business in the United Kingdom continued to develop positively and accounted for more than 20% of total group revenue in the 2025 financial year.

The positioning of Cantourage Group SE as a pan-European pharmaceutical company is showing increasingly positive effects. Economies of scale, optimized supply chains, and a diversified market presence are stabilizing operational development.

“The European medical cannabis market is increasingly entering a new phase of growth. With our scalable sourcing and distribution platform, exclusive supplier partnerships, and regulatory expertise, we are ideally positioned to benefit from this development. Our focus is on meeting rising demand in our core markets, further expanding our capacities, and establishing Cantourage as one of the leading companies in all relevant European medical markets,” explains Philip Schetter, CEO of Cantourage Group SE.

Price competition in the German market – focus on high-margin premium products

Profitability development in the German market in 2025 was affected by increasing price competition in the low-price segment of medical cannabis flowers. This was driven by a significant increase in product supply in the market, which led to noticeable price pressure, particularly during the summer months.

Cantourage is responding to this market development in Germany by specifically adjusting its product portfolio and placing greater emphasis on higher-margin premium products. In doing so, the company benefits from its international network of selected cultivation partners, with whom Cantourage has established long-term and largely exclusive supply relationships.

From management’s perspective, this strategic direction strengthens the structural profitability of the business in the German market while simultaneously reducing dependence on the increasingly competitive low-price segment.

Note: The figures for the 2025 financial year presented in this release are preliminary, unconsolidated, and unaudited. The audited consolidated financial statements for 2024 are available at: https://www.cantourage.com/investoren#konzernabschluesse


17.03.2026 CET/CEST Dissemination of a Corporate News, transmitted by EQS News – a service of EQS Group.
The issuer is solely responsible for the content of this announcement.

The EQS Distribution Services include Regulatory Announcements, Financial/Corporate News and Press Releases.


Language: English
Company: Cantourage Group SE
Feurigstraße 54
10827 Berlin
Germany
E-mail: info@cantourage.com
Internet: https://www.cantourage.com/
ISIN: DE000A3DSV01
WKN: A3DSV0
Listed: Regulated Unofficial Market in Dusseldorf, Frankfurt (Scale), Munich, Stuttgart, Tradegate BSX
EQS News ID: 2292732

 
End of News EQS News Service

2292732  17.03.2026 CET/CEST

Imprivata Introduces New Advanced Access Management and Passwordless Authentication Capabilities to Address Evolving NHS Cyber Security and Compliance Challenges

Imprivata Introduces New Advanced Access Management and Passwordless Authentication Capabilities to Address Evolving NHS Cyber Security and Compliance Challenges


Imprivata Introduces New Advanced Access Management and Passwordless Authentication Capabilities to Address Evolving NHS Cyber Security and Compliance Challenges

Imprivata Enterprise Access Management now offers facial recognition, AI-powered behavioral analytics, and high-assurance identity verification to further streamline access to personal and shared-use devices, increase operational efficiency, and strengthen security and compliance posture

LONDON, March 17, 2026 (GLOBE NEWSWIRE) — Imprivata, a leading provider of access management solutions for healthcare and other mission-critical industries, today introduced comprehensive new capabilities designed to help NHS organisations and UK healthcare providers meet the unique demands of the UK’s evolving compliance, cybersecurity, data protection landscape, including the Cyber Assessment Framework (CAF)-aligned Data Security and Protection Toolkit (DSPT) and Care Identity Service (Spine) Authentication.

Imprivata Enterprise Access Management (EAM) now offers context-aware passwordless authentication, high-assurance identity verification, and AI-powered behavioral analytics, expanding the company’s leading solutions for improving workflow productivity while meeting the unique demands of the UK’s evolving compliance, cybersecurity, and data protection landscape.

“Providers and Trusts across the NHS system continue to rely on Imprivata to deliver solutions that remove workflow friction while bolstering security. As UK healthcare organisations face evolving compliance and operational challenges, our expanded EAM platform will help them meet these new requirements while ensuring clinicians have fast, seamless access to the resources they need to care for patients,” said Fran Rosch, CEO of Imprivata. “Imprivata EAM delivers these workflow, security, and compliance benefits from a single, comprehensive platform, which also helps reduce cost and drive meaningful return on technology investment, which is critical as budgets continue to tighten.”

Addressing UK-Specific Identity and Access Challenges

UK health and care systems are under increasing pressure to adopt modern, standards-based approaches to identity, authentication, and access control, while demonstrating compliance to national assurance frameworks such as the CAF-aligned DSPT and NHS England Spine Authentication, a modern, standards-based identity authentication service. These and other initiatives underscore the need for strong authentication and access management practices across NHS organisations.

The new EAM functionality delivers tailored capabilities that support NHS identity and cyber security priorities:

  • CAF-Aligned DSPT & Identity Assurance: Advanced access management and passwordless authentication help NHS organisations strengthen identity assurance, reduce reliance on shared credentials, and demonstrate multi-factor authentication (MFA) controls required under regional requirements such as the CAF-aligned DSPT. This includes detailed reporting and audit trails to support toolkit submission and independent assessment evidence.
  • Seamless Passwordless Experience: Clinicians and care staff benefit from friction-free, secure login methods that reduce login fatigue, increase productivity, and align with NHS workforce needs. These options support the wide range of authenticators and help drive adoption of secure access without compromising user experience.
  • Role-Based Access and Audit-Ready Controls: Built-in role and attribute-aware policies ensure that authenticated users are granted precisely the access they need, helping NHS organisations demonstrate cyber framework compliant access control and accountability while reducing the surface for misuse or lateral movement.

Imprivata EAM addresses these challenges by delivering a unified access management platform to support all enterprise users and workflows while also enabling a seamless, consistent user experience. The platform supports a wide variety of authenticator options and combinations to give users the flexibility to meet their specific requirements and preferences. Platform capabilities include:

  • Advanced passwordless authentication, including support for integrated face authentication technology to improve security while simplifying access for users
  • High-assurance identity verification to enable secure onboarding, help desk authentication, and self-service password reset
  • Risk signaling and behavioral analytics to determine and respond to potential security threats associated with users accessing corporate resources
  • Secure access for VPN-less remote access built on Zero Trust principles to provide a seamless experience for users outside the network
  • Operational analytics that provide near real-time workflow and access data to drive more informed, strategic decisions

Interested in learning more?
Imprivata offers several different ways to learn more about Imprivata EAM and the expanded functionality:

  • Imprivata will demonstrate the new functionality of EAM during Digital Health Rewired 2026 (24-25 March, 2026, The NEC, Birmingham) in Hall 4. To book a demo at Digital Health Rewired, visit here.
  • Watch our on-demand webinar for a first look at the new features
  • Register Now to attend our live webinar “Next generation of Imprivata Enterprise Access Management for the NHS” on Thursday, April 30, 2026 at 11a.m. GMT.
  • Request a demo here.

About Imprivata 
Imprivata delivers simple and secure access management solutions for healthcare and other mission-critical industries to ensure every second of crucial work is both frictionless and secure. Imprivata’s platform of innovative, interoperable access management and privileged access security solutions enable organisations to fully manage and secure all enterprise and third-party identities to facilitate seamless user access, protect against internal and external security threats, and reduce total cost of ownership. For more information, visit www.imprivata.com.
 
Media Contact
press@imprivata.com

Sartorius Stedim Biotech sharpens strategy with biopharma focus and sets new mid-term growth targets

Sartorius Stedim Biotech SA

/ Key word(s): Forecast

Sartorius Stedim Biotech sharpens strategy with biopharma focus and sets new mid-term growth targets

17-March-2026 / 07:03 CET/CEST


Aubagne, France | March 17, 2026

Sartorius Stedim Biotech sharpens strategy with biopharma focus and sets new mid-term growth targets

 
  • Expanding leading position with biopharma customers in attractive growth markets
  • Strengthening competitive edge with focus on high-growth, high-margin core portfolio and emerging businesses
  • New ambitious mid-term targets set clear path for sustained, profitable growth above market
Sartorius Stedim Biotech, a leading provider of innovative technologies for the manufacture of biologics, is sharpening its strong focus on biopharma customers and outlined its updated strategy and new mid-term financial targets ahead of today’s Capital Markets Day, defining a clear trajectory for sustained above‑market growth.

“Our resilient business model and strong execution over recent years provide an excellent starting point for the next growth phase,” said Dr. René Fáber, Chief Executive Officer of Sartorius Stedim Biotech. “The biopharma industry faces increasing demands for efficiency, scalability and reliability. We want to address these even better by extending our leadership position in core bioprocessing technologies and building future growth platforms in areas such as advanced therapies and process analytics. With this, we aim to continue to outperform our markets and create long-term value for customers, partners, suppliers, employees and shareholders alike.”

Sartorius Stedim Biotech’s refined strategic focus reflects key developments in the biopharmaceutical industry. Biologics account for a growing share of pipelines, approvals, and manufacturing volumes. In 2025, global biopharma revenues surpassed those of traditional therapies for the first time and are projected to reach around 57percent of global pharma sales by 2030. At the same time, the industry is becoming more complex, driven by emerging new modalities and mounting cost pressures on health care systems. 
 

Strategic initiatives: Driving portfolio evolution, customer experience and efficiency
To continue its strong growth momentum and further expand its established market position in this changing environment, Sartorius Stedim Biotech has defined a set of strategic initiatives.

With regard to its product portfolio, the company aims to further strengthen its core business by reinforcing its leadership positions in mission critical applications in process intensification, single-use technologies and analytics. In addition, Sartorius Stedim Biotech plans to further develop select emerging businesses, including process analytical technologies and offerings for advanced therapy solutions – a dynamically growing market that particularly requires continuous innovation.

Beyond its portfolio, Sartorius Stedim Biotech is responding to shifting expectations within the biopharma industry, including shorter lead times, delivery reliability and more streamlined interactions. To support this, the company is putting customers even more firmly at the center of its actions while systematically enhancing operational efficiency across supply chain performance, product quality and service performance.

Mid-term ambition: Above-market organic sales revenue growth and margin expansion

Based on its assessment of future market development, Sartorius Stedim Biotech expects the bioprocessing market to expand at a rate of approximately 8 to 10 percent per year over the medium term. Against this backdrop and building on its leading market position as well as its focused strategy, Sartorius Stedim Biotech introduced a new mid‑term ambition for the period from 2027 onwards. Management expects the company to consistently outgrow its addressable market by around 100 to 200 basis points per year, targeting organic sales revenue growth of 9 to 12 percent per year in constant currencies. At the same time, Sartorius Stedim Biotech is committed to further expanding its profitability: The underlying EBITDA margin1 is expected to increase by approximately 60 to 85 basis points per year, driven by operating leverage, operational improvements and a growing share of high-margin consumables.

1 Sartorius Stedim Biotech publishes alternative performance measures that are not defined by international accounting standards. These are determined with the aim of improving comparability of business performance over time and within the industry.

  • Constant currencies: figures given in constant currencies eliminate the impact of changes in exchange rates by applying the same exchange rate for the current and the previous period
  • Underlying EBITDA: earnings before interest, taxes, depreciation, and amortization and adjusted for extraordinary items

2 EMEA = Europe, Middle East, Africa

This media release contains forward-looking statements about the future development of the Sartorius Stedim Biotech Group. Forward-looking statements are subject to known and unknown risks, uncertainties, and other factors that could cause actual results to differ materially from those expressed or implied by such statements. Sartorius Stedim Biotech assumes no liability for updating such statements in light of new information or future events. Sartorius Stedim Biotech shall not assume any liability for the correctness of this release. The original French press release is the legally binding version.

Forecasts have been prepared based on historical information and are consistent with accounting policies. All forecast figures are based on constant currencies, as in past years. Management points out that the dynamics and volatilities in the industry have increased significantly in recent years. In addition, uncertainties due to the changed geopolitical situation, such as the emerging decoupling tendencies of various countries as well as the trade policy framework conditions, are playing a greater role. This results in higher uncertainty when forecasting business figures.

Further information
Sartorius Stedim Biotech Capital Markets Day

Financial calendar
March 24, 2026 | Annual General Meeting 
April 23, 2026 | Publication of quarterly figures for January to March 2026 
July 23, 2026 | Publication of half-year figures for January to June 2026 
October 22, 2026 | Publication of nine-month figures for January to September 2026

A profile of Sartorius Stedim Biotech

Sartorius Stedim Biotech is a leading international partner of the biopharmaceutical industry. As a provider of innovative solutions, the company based in Aubagne, France, helps its customers to manufacture biotech medications, such as cell and gene therapies, safely, rapidly, and sustainably. The shares of Sartorius Stedim Biotech S.A. are quoted on the Euronext Paris. The company has a strong global reach with manufacturing and R&D sites as well as sales entities in Europe, North America, and Asia. Sartorius Stedim Biotech regularly expands its portfolio through acquisitions of complementary technologies. In 2025, the company generated sales revenue of around 3 billion euros. Currently, more than 10,200 employees are working for customers around the globe.

Visit our newsroom and follow us on LinkedIn.

Contact 
Leona Malorny 
Head of External Communications 
+49 551 308 4067 
leona.malorny@sartorius.com


Attachment

File: Sartorius Stedim Biotech sharpens strategy with biopharma focus and sets new mid-term growth targets | Media release


Dissemination of a Financial Wire News, transmitted by EQS Group.
The issuer is solely responsible for the content of this announcement.


2292110  17-March-2026 CET/CEST

PolyPeptide publishes invitation to the annual General Meeting 2026

PolyPeptide Group

/ Key word(s): AGMEGM

PolyPeptide publishes invitation to the annual General Meeting 2026

17.03.2026 / 07:00 CET/CEST


Media release

PolyPeptide publishes invitation to the annual General Meeting 2026

Baar, 17 March 2026 – PolyPeptide Group AG (SIX: PPGN), a specialized global CDMO for peptide-based active pharmaceutical ingredients, published today the invitation to the fifth annual General Meeting, which will take place on 8 April 2026 at the Chollerhalle in Zug.

At PolyPeptide Group AG’s (the “Company”) fifth annual General Meeting, which will take place on 8 April 2026 at the Chollerhalle in Zug (the “AGM 2026”), all six current members of the Board of Directors will stand for re-election. Peter Wilden is proposed for re-election as Chair of the Board of Directors, and Philippe Weber and Peter Wilden as members of the Remuneration and Nomination Committee.

Further proposals include, among others, the re-election of the Statutory Auditors and the Independent Proxy as well as the approval of the maximum aggregate amount of compensation of the Board of Directors and Executive Committee. The shareholders will also be asked to approve the Management Report, Statutory Financial Statements, Consolidated Financial Statements and the report on non-financial matters, in each case, for the financial year 2025 as well as the Remuneration Report 2025 in a separate consultative vote.

The invitation to the AGM 2026 with the detailed proposals and explanations can be found on the Company’s website.

Contact

PolyPeptide Group AG      
Corporate Communications   
Lauren Starr      
mediateam@polypeptide.com     
T: +41 43 502 0580     

PolyPeptide Group AG
Investor Relations 
Tim Brandl 
investorrelations@polypeptide.com 
T: +41 43 502 0580 

About PolyPeptide

PolyPeptide Group AG and its consolidated subsidiaries (“PolyPeptide”) is a specialized Contract Development & Manufacturing Organization (CDMO) for peptide-based active pharmaceutical ingredients. By supporting its customers mainly in pharma and biotech, it contributes to the health of millions of patients across the world. PolyPeptide serves a fast-growing market, offering products and services from pre-clinical to commercial stages. Its broad portfolio reflects the opportunities in drug therapies across areas and with significant exposure to metabolic diseases, including GLP-1. Dating back to 1952, PolyPeptide today runs a global network of six GMP-certified facilities in Europe, the U.S. and India. PolyPeptide’s shares (SIX: PPGN) are listed on SIX Swiss Exchange.

For more information, please visit polypeptide.com.  

@PolyPeptide — follow us on LinkedIn.

Disclaimer

This media release has been prepared by PolyPeptide Group AG and contains certain forward-looking statements that reflect the current views of management. Such statements are subject to known and unknown risks, uncertainties and other factors that may cause actual developments to differ materially from those expressed or implied in this release. PolyPeptide Group AG is providing the information in this release as of this date and, except as required by applicable laws or regulations, does not undertake any obligation to update any statements contained in it as a result of new information, future events or otherwise.


Additional features:

File: Polypeptide Media release AGM 2026 Invitation (English)


End of Media Release


Language: English
Company: PolyPeptide Group
Neuhofstrasse 24
6340 Baar
Switzerland
Phone: +41435020580
E-mail: mediateam@polypeptide.com
Internet: www.polypeptide.com
ISIN: CH1110760852
Valor: 111076085
Listed: SIX Swiss Exchange
EQS News ID: 2292198

 
End of News EQS News Service

2292198  17.03.2026 CET/CEST

Medartis builds on momentum with 16% organic sales growth and core EBITDA margin exceeding 18%

 ​​​​​FULL-YEAR 2025 KEY FINANCIALS


in CHF million, rounded


FY 2025


FY 2024


Organic growth1
of core business


Reported

Non-core
items2

Core

Reported

Non-core
items2

Core

in CHF

at CER

Net sales

269.3

(3.2)

266.1

224.8

(5.2)

219.6

12.0%

15.7%

Gross profit

204.3

11.3

215.6

178.7

3.1

181.7


EBITDA

51.5

(2.6)

48.8

48.0

(6.3)

41.7


EBIT

26.0

(1.5)

24.5

7.9

12.9

20.8


Net profit / loss

9.3

(3.2)

6.1

3.5

7.9

11.4


Margins in % of sales


Core change as
%-points (PP)

Gross profit

75.9%


81.0%

79.5%


82.8%

(1.7 PP)

(1.1 PP)

EBITDA

19.1%


18.4%

21.4%


19.0%

(0.6 PP)

0.6 PP

EBIT

9.7%


9.2%

3.5%


9.5%

(0.2 PP)

1.2 PP

Basel, 17 March 2026: Medartis Holding AG (MED:SW), a leading orthopaedic company specialising in head and extremity surgery, today reported total sales of CHF 269.3 million for the full year 2025, representing growth of 24.2% at constant exchange rates (CER). Organically, sales rose 15.7% (2024: 11.7%). EMEA was the principal growth driver, advancing by 18.0% and gaining further market share. The strong topline growth enabled Medartis to meet its initial EBITDA margin guidance despite adverse currency effects and US customs tariffs.


Matthias Schupp, CEO of Medartis, comments on the result: “2025 was a transformative year for Medartis and we achieved our goals by increasing organic sales by 15.7% and maintaining our core EBITDA margin at 18.4% despite significant currency and customs burdens. The acquisition of KeriMedical and NeoOrtho establishes the Medartis Group with three distinctive brands and a multi-tier strategy, expanding our addressable market significantly. We have also strengthened our leadership team, restructured our distribution channels in the United States and Japan, and positioned the company for accelerated growth as part of our head-to-toe strategy.”


Acquisitions add over CHF 800 million to addressable market, with further upside

Medartis completed two acquisitions during 2025. The KeriMedical partnership, which commenced in 2020, reached completion in July following FDA approval for the flagship TOUCH prosthesis. Medartis now holds 100% ownership of KeriMedical, strengthening the company’s position in arthroplasty and marking its entry into this segment. Separately, Medartis acquired a 51% controlling stake in NeoOrtho, a fast-growing value player in the Brazilian orthopaedic market. The acquisition enables a multi-tier pricing strategy and expands the company’s presence in Latin America. It represents a strategic entry into the estimated CHF 450 million value market segment in the region, which currently accounts for approximately three-quarters of the total market.


Together, these transactions expand Medartis’ addressable market by more than CHF 800 million, based on current market estimates in the segments where the company is active; the long-term potential is estimated to be considerably larger as these segments continue to grow and the company expands its geographical reach. Beyond portfolio expansion, they form part of a broader organisational evolution as Medartis transitions from a centralised, Swiss precision-oriented structure to a more decentralised, multi-brand model. This shift is designed to enable the company to compete more effectively across diverse global markets with differing customer needs and competitive dynamics.


Strategic step into personalised implants and titanium printing

With the publication of today’s results, Medartis also announced that it has entered an agreement to acquire CADskills, a Belgium-based specialist in personalised implant solutions and titanium printing, two fast-evolving areas in extremity and head (CMF) surgery. The acquisition reinforces Medartis’ strategic focus on more complex clinical applications with custom-made implants — including replacement of the jaw joint[2], implants designed to sit directly on the bone surface for patients with significant bone loss[3], and facial contouring solutions[4]. CADskills holds certification to manufacture class III medical devices — the highest regulatory classification for implants. The company has also developed deep expertise in titanium 3D printing and operates a highly integrated model encompassing design, manufacturing and packaging. These printing capabilities are transferable to other regions in the future, supporting Medartis’ broader geographic expansion.


In addition, the acquisition expands Medartis’ upper extremity replacement offerings through the Carpitech™ family, which includes carpal bone arthoplasties, further consolidating Medartis’ position as a market leader in small bone replacement in the hand.


CADskills was founded by Prof. Dr mult. Dr Maurice Mommaerts, whose work and research in patient-specific implant design and additive manufacturing has contributed to advancing the field. Following the integration in the Medartis Group, Mr Mommaerts will provide scientific and clinical expertise to support continuity during the expansion phase. The transaction is structured as an upfront payment complemented by sales-based earnout components. Both parties have agreed not to disclose exact financial details. Closing of the transaction remains subject to the fulfilment of certain conditions, including a successful Foreign Direct Investment (FDI) screening in Belgium.


PERFORMANCE BY REGION AND PRODUCT CATEGORY


Core sales
in CHF million

FY 2025
 

FY 2024
 

Change
in CHF

Change at CER

Organic change
at CER

EMEA

155.4

122.8

26.5%

28.5%

18.0%

US1

50.4

47.1

7.0%

13.4%

13.4%

APAC

33.4

31.1

7.3%

14.0%

13.3%

LATAM1

26.8

18.5

44.9%

57.1%

10.4%

Total Group

266.1

219.6

21.2%

25.6%

15.7%

1 The NSI contract manufacturing business and NeoOrtho’s hip business, which was divested in 2025, were classified as non-core.


In the EMEA region, core sales rose substantially from CHF 122.8 million in 2024 to CHF 155.4 million in 2025, reflecting growth of 28.5% at constant exchange rates. The acquired KeriMedical business contributed CHF 14.1 million to the topline since its consolidation in July 2025. Organically, sales rose 18.0% (CER). The UK and Spain were the primary contributors to the 18.0% growth. In Germany, the company’s largest market in Europe, results were solid despite some impact from the transition to the new hybrid DRG reimbursement system[5] for lower extremities. This performance enabled the company to capture additional market share in the region, driven by the expansion of its elbow portfolio, KeriMedical product sales, and greater territorial coverage thanks to a strengthened sales team. The KeriMedical business, currently distributed directly in three markets, accounted for one quarter of regional growth.

The 2025 EMEA performance surpassed expectations. Medartis secured a significant tender in Saudi Arabia and established market access in Malta and the Baltic countries. In Switzerland, the company introduced its new Hand 2 portfolio, strengthened its presence in the French-speaking region, and benefitted from a substantial CMF contract with the region’s largest university clinic.


Core sales
in CHF million

FY 2025
 

FY 2024
 

Change
in CHF

Change
at CER

Organic change
at CER

Upper Extremities

179.9

148.2

21.4%

25.7%

15.7%

Lower Extremities

47.3

40.7

16.4%

21.0%

15.1%

CMF and Others1

38.8

30.7

26.4%

31.3%

16.8%

Total Group

266.1

219.6

21.2%

25.6%

15.7%

1 The NSI contract manufacturing business and NeoOrtho’s hip business, which was divested in 2025, were classified as non-core.


Fundamental changes completed in the US

Medartis’ core US business achieved organic growth of 13.4% at constant exchange rates. Despite a weakening US Dollar, which reduced reported sales by over 6%-points, sales exceeded the CHF 50 million threshold for the first time in the company’s history. The declining contract manufacturing business from the former NSI contributed CHF 1.8 million in sales to total sales, down from CHF 5.2 million in 2024.


Growth moderated in H2 primarily due to the strategic sales channel optimisation, during which the company replaced approximately half of its 57 distribution partners to achieve greater brand and product exclusivity in operating theatres. Following the optimisation, the company now operates with 65 distribution partners. Mid-year, the company terminated its relationship with its largest distribution partner in Florida, accounting for nearly 10% of US sales, to address fundamental issues that would have constrained future growth in the region. The affected territories were refilled rapidly and coverage was expanded through five new distributors across Florida, with complete integration expected within 12 months from the onset of the transition. The company also appointed a new regional sales manager for the Southeast region Orlando and Tampa, positioning itself to capitalise on its first US training centre in Orlando, scheduled to open in Q4. Florida represents a strategically important market for TOUCH, given the population density and age demographics in this retirement state. Excluding the unexpected change in Florida, full-year growth would have reached 18%.


Concurrent with these developments, the company launched the Avenger radial head prosthesis and prepared for the commercial rollout of TOUCH in 2026, with initial cases performed by key opinion leaders (KOL) and product registration completed in first-mover centres. The registration process through a value analysis committee (VAC) averages up to four months. To support this important launch, Medartis recruited 10 specialists – comprising field experts and education specialists –and established a train-the-trainer programme designed to train more than 300 surgeons with hands-on support in 2026.


A strategic portfolio review resulted in streamlining efforts, including the discontinuation of former NSI products, allowing Medartis to concentrate more resources on upper extremities. The year marked an important transition for the region, with FDA approvals, sales channel optimisation, portfolio streamlining, and leadership changes positioning the company for sustained growth. Management anticipates that TOUCH will serve as a catalyst for business expansion and broaden the surgeon base.


Sales in the APAC region increased from CHF 31.1 million in 2024 to CHF 33.4 million in 2025, representing growth of 14.0% (CER) and strong currency headwind. Excluding a minor acquisition effect from KeriMedical sales in the region, organic sales growth reached 13.3% (CER). The Asia Pacific region returned to double-digit growth after two years of challenging market conditions. With the adverse pricing impact ceasing in mid-2025 and fuelled by distal radius growth in excess of 9%, Medartis’ Australian business achieved solid performance. Following the first full year of TOUCH product sales, reimbursement approval remains pending. The clinician feedback for TOUCH is positive and the clinical appetite for the basal thumb prostheses remains high. Medartis anticipates a reimbursement decision in H1, which is expected to establish pricing for CMC1[6] arthroplasty on the ‘Prescribed List’ and stimulate patient flow. The Japanese business recorded growth in excess of 50% as the transition to direct distribution for the upper extremity portfolio progressed. New surgeon acquisition and customer conversion from the former local distributor continued to advance, albeit at a slower pace than initially anticipated. The company’s CMF distributor in Japan exceeded planned targets for the Modus product line, whilst APAC distributors delivered single-digit growth, slightly below internal projections.


Latin America recorded a turnaround following the regional sales decline in the prior year. Core regional sales in 2025 advanced by 57.1% (CER) to reach CHF 26.8 million. The acquired NeoOrto business contributed CHF 8.3 million to the topline since its consolidation in May 2025. Organically, sales rose 10.4% (CER). In Mexico, sales grew in the double-digit range, where the company completed a successful reorganisation, transitioning to a direct sales model in Mexico City under the new leadership, which is demonstrating early potential. Distributor sales grew robustly. The Brazilian business stabilised, with a notable improvement in the strategically important CMF segment. Medartis defined a new price positioning for the market and sharpened its commercial focus on the principal urban areas. Through the “Cold Fusion” programme, Medartis is merging the back-office and support functions of Medartis LATAM and NeoOrtho in Curitiba.


The consolidation is expected to generate operational synergies from 2027 onwards and provide the scale required to support regional growth. The new production facility progressed according to plan and is set to be inaugurated at the end of March 2026. Beyond this integration, Medartis is preparing market entries with both brands in Colombia, Argentina, and Chile during 2026 and 2027. The Latin America strategy is intended to serve as a template for entering other value markets in the future.


FINANCIAL PERFORMANCE


This media release and other investor and financial press communications include Alternative Performance Measures (APMs), which exclude one-time effects and M&A-related intangible asset amortisation to provide a clearer view of the company’s underlying operating performance. Medartis management uses these metrics to assess Medartis’ financial and operational performance, providing a complementary perspective to standard financial figures as defined by IFRS. To derive the core result for 2025, the following items were excluded from the reported IFRS figures.


  • Under ‘non-core business,’ the negative gross profit contribution of CHF 1.3 million from the US contract manufacturing business and the NeoOrtho hip business were excluded from the core results. The former is scheduled for phase-out in the near term, while the latter was divested in H2.
  • Transaction costs of CHF 0.6 million, recorded in general and administrative expenses, relate to the NeoOrtho and KeriMedical acquisitions. The transition of the Swiss pension fund from an insurance-based model to a collective foundation required adjustments to asset and liability recognition under IAS 19, resulting in additional past service costs of CHF 6.6 million. These were classified under ‘others’ and affected both COGS and OPEX. A further CHF 3.0 million was recorded for product write-offs and a legal settlement following the strategic portfolio review and discontinuation of former NSI products.
  • The largest adjustment to the reported IFRS figures related to post ‘M&A effects’, comprising: the amortisation of inventory step-up to fair value of CHF 8.8 million; a revaluation of the historical 49% investment in KeriMedical of CHF 14.5 million; and a release of CHF 8.6 million in contingent consideration liabilities related to the final NSI earn-out payment. The M&A effects together with some smaller items had a positive impact of CHF 13.6 million on reported EBITDA.


The following commentary compares the core results for 2025 with those of the prior-year period on a like-for-like basis.


In 2025, core gross profit declined by 1.8PP from 82.8% to 81.0%. The gross margin decline reflected unanticipated US tariff-related costs (0.9 PP), foreign exchange headwinds (0.6 PP) and costs associated with capacity expansion across all four manufacturing sites ahead of anticipated demand growth. Manufacturing efficiency improvements provided a partial offset. The premium KeriMedical product portfolio had an accretive effect on the gross margin, whereas the NeoOrtho value business was dilutive owing to lower average selling prices relative to the premium range.


Core operating expenses (OPEX) increased at a slower rate than revenue. With OPEX of CHF 194.6 million, the OPEX-to-sales ratio decreased from 73.8% in the prior year to 73.1% in 2025, reflecting disciplined cost management despite continued investment in growth initiatives. Ahead of the FDA approval, the company build-up of the support organisation for the TOUCH rollout in the US and Australia. Excluding the aforementioned non-core elements, and before taxes, D&A and interest, core EBITDA rose from CHF 41.7 million to CHF 48.8 million. The corresponding EBITDA margin declined from 19.0% to 18.4%. This is mainly a result of the lower gross profit margin. The core EBIT margin decreased by 0.2PP to 9.2%, though it improved by 1.2PP on a constant currency basis.


The core net result declined from CHF 11.4 million in 2024 to CHF 6.1 million in 2025. This was primarily attributable to the factors outlined above and a lower finance result. In 2025, interest expense on the convertible bond amounted to CHF 3.5 million, with a further CHF 3.3 million in accretion expenses. The higher year-on-year charges reflect the first full-year impact of the convertible bond, which was issued in April 2024 and therefore only affected approximately nine months of the prior-year period (2024 interest expense: CHF 2.5 million). In addition, FX losses of CHF 5.3 million were recorded, mainly related to the depreciation of the US dollar and the Australian dollar. Core income tax expenses of CHF 5.2 million were recorded in 2025, compared to an exceptional income tax credit of CHF 1.0 million in 2024.


Operating cash flow increased by CHF 2.7 million to CHF 34.8 million, and free cash flow reached CHF 9.3 million, reflecting CHF 14.4 million in additional capital expenditure compared with the prior year as the company invested heavily in new production machinery in its facilities in the Warsaw, US, Archamps, Besançon, Curitiba and Basel. M&A-related cash outflows totalled CHF 120.8 million, comprising the equity investment in NeoOrtho and the cash consideration as well as the first of three earn-out payments for KeriMedical. At year-end, the company’s cash position stood at CHF 33.0 million (PY: CHF 138.7 million). For further information on the company’s financial performance, please refer to the financial section of the 2025 Annual Report, available on the company’s website.


NEW BOARD MEMBER PROPOSED

At the upcoming Annual General Meeting on 23 April 2026, shareholders will be asked to elect Yang Xu to the Board of Directors. Ms Xu currently serves as Chief Financial Officer of JDE Peets. Prior to this role, she held the position of CFO at the Straumann Group. She will succeed Jennifer Dean, who has served as a member of the Board and the Finance and Audit Committee since 2024. Ms Dean has decided not to stand for re-election. The Board thanks her for her contributions.


FULL-YEAR 2026 OUTLOOK

(barring any unforeseen circumstances)


Medartis expects to strengthen its market position in the US in 2026, supported by the continued rollout of KeriMedical’s TOUCH prosthesis, alongside continued progress in Japan and further expansion across Latin America. As the number of surgeons trained on TOUCH in the US increases progressively, regional sales growth is anticipated to be stronger in the second half of the year than in the first. Based on its assumptions, the company expects organic growth in core sales[7] 16% – 18% over the full-year.


The company also expects a core EBITDA margin in the high teens (at CER), reflecting planned investments in growth initiatives and ongoing TOUCH rollout in the US and Australia.


————————————————————————————————————

Medartis to Host Full-Year 2025 Results Conference with Q&A

Medartis will present its full-year 2025 results today at 10:30 a.m. CET at its headquarters in Basel.
CEO Matthias Schupp and CFO Peter Hackel will host the event. The conference will be held in English. The presentation materials, Annual Report and a recording of the event are available on the Medartis website (https://medartis.com/en/investors#reports).

If you cannot attend in person, use the webcast link to register and follow the slide presentation and submit questions in writing or via the webcast interface.

IMPORTANT DATES AND UPCOMING INVESTOR EVENTS

Date

Event

Broker

Destination

17 March

2025 full-year results publication


Basel, hybrid

18 March

Investor meetings

ZKB

Zurich

19 March

Investor meetings

UBS

Geneva

20 March

Investor meetings

Octavian

Frankfurt

24 March

Investor meetings

UBS

Paris

20 April

Investor meetings

Kepler Cheuvreux

New York

21 April

Investor meetings

Kepler Cheuvreux

Montreal

23 April

Annual General Meeting 2025


Basel, HQ

11 Mai

Investor meetings

Stifel

London

12 Mai

European Small and Midcap Conference

UBS

London

3-4 June

Medartis Group Visitor Day (FESSH congress)


Basel

18 August

2026 half-year results publication


Webcast

5-7 November

Swiss Equity Conference

ZKB

Zurich, CH

Legend: Events highlighted in italic are broadcasted online


Your contact:

Medartis Corporate Communications

Fabian Hildbrand, Head of Corporate Communications, investor.relations@medartis.com

Andreas Richter, Corporate Communications Manager, corporate.communication@medartis.com

+41 61 633 37 36 / +41 61 633 37 34


About Medartis

Founded in 1997 and headquartered in Basel, Switzerland, the Medartis Group is one of the world’s leading manufacturers and providers of medical devices for surgical fixation of bone fractures and joint replacement for upper and lower extremities as well as for the craniomaxillofacial region. The Group has manufacturing sites in Switzerland, the United States, Brazil, and France. Medartis employs approx. 1,400 individuals across 12 countries, with products offered in over 60 countries globally. Medartis is committed to providing surgeons and operating theatre personnel with the most innovative implants and instruments as well as best-in-class service. For more information, please visit www.medartis.com.


Disclaimer

This communication does not constitute an offer or invitation to subscribe for or purchase any securities of Medartis Holding AG. This publication may contain certain forward-looking statements and assessments or intentions concerning the company and its business. Such statements involve certain risks, uncertainties and other factors which could cause the actual results, financial condition, performance or achievements of the company to be materially different from those expressed or implied by such statements. Readers should therefore not place reliance on these statements, particularly in connection with any contract or investment decision. The company disclaims any obligation to update these forward-looking statements, assessments or intentions. Furthermore, neither the company nor any of its directors, officers, employees, agents, counsel or advisers nor any other person makes any representation or warranty, express or implied, as to the accuracy or completeness of the information contained herein or of the views given or implied, and accordingly no reliance should be placed thereon.


[1],2 This report and accompanying financial documents include alternative performance measures (APMs), referred to as “core” figures, which provide additional insight into Medartis’ underlying performance. Core figures exclude certain one-time, non-recurring and extraordinary items or items related to M&A. The NSI contract manufacturing business and NeoOrtho’s hip business (divested in H2 2025) contributed CHF 3.2 million to total revenue and were classified as non-core. For a detailed overview of all non-core events in the Income Statement, please refer to APM section of the Annual Report. Organic growth is calculated using fixed exchange rates (CER). To ensure fair comparison, it includes the acquired business’s sales in the baseline figures from the date Medartis assumed control.

[2] Temporomandibular joint replacement, TMJR Parametro™

[3] Subperiosteal implants, AMSJI®™ = Additively Manufactured Subperiosteal Jaw Implant

[4] Facial contouring

[5] DRG = Diagnosis-Related Group. Reimbursement is calculated by applying a indication specific multiplier to a standardised base rate.

[6] Thumb osteoarthritis (CMC = carpometacarpal joint arthritis)

[7] “Organic growth” denotes the increase in sales at constant exchange rates (CER), excluding the sales from acquired or sold businesses (i.e. NeoOrtho, KeriMedical) in the baseline. NSI’s contract manufacturing business and divested NeoOrtho hip business were non-core activities.

Pennant Group to Participate in the 2026 Oppenheimer Annual Healthcare Conference

Pennant Group to Participate in the 2026 Oppenheimer Annual Healthcare Conference


Pennant Group to Participate in the 2026 Oppenheimer Annual Healthcare Conference

EAGLE, Idaho, March 16, 2026 (GLOBE NEWSWIRE) — The Pennant Group, Inc. (NASDAQ: PNTG), the parent company of the Pennant group of affiliated home health, hospice and senior living companies, announced today that it will participate in the upcoming 2026 Oppenheimer Co. Annual Healthcare MedTech & Services Conference on March 18, 2026.

Brent Guerisoli, Chief Executive Officer, and Lynette Walbom, Chief Financial Officer will participate in a fireside chat on March 18, 2026 at 9:40 a.m. Eastern Time. A live webcast of the event will be accessible at the following address:
investor.pennantgroup.com/events-and-presentations.

About Pennant

The Pennant Group, Inc. is a holding company of independent operating subsidiaries that provide healthcare services throughout the United States. Each of these businesses is operated by a separate, independent operating subsidiary that has its own management, employees and assets. References herein to the consolidated “company” and “its” assets and activities, as well as the use of the terms “we,” “us,” “its” and similar verbiage, are not meant to imply that The Pennant Group, Inc. has direct operating assets, employees or revenue, or that any of the home health and hospice businesses, senior living communities or the Service Center are operated by the same entity. More information about Pennant is available at www.pennantgroup.com.

Contact Information

The Pennant Group, Inc.
(208) 506-6100
ir@pennantgroup.com

SOURCE: The Pennant Group, Inc.

Zenas BioPharma Announces Inducement Grants Under Nasdaq Listing Rule 5635(c)(4)

Zenas BioPharma Announces Inducement Grants Under Nasdaq Listing Rule 5635(c)(4)


Zenas BioPharma Announces Inducement Grants Under Nasdaq Listing Rule 5635(c)(4)

WALTHAM, Mass., March 16, 2026 (GLOBE NEWSWIRE) — Zenas BioPharma, Inc. (“Zenas” or the “Company”) (Nasdaq: ZBIO), a clinical-stage global biopharmaceutical company committed to being a leader in the development and commercialization of transformative therapies for patients living with autoimmune diseases, today announced that on March 16, 2026 (the “Grant Date”), the Compensation Committee of the Company’s Board of Directors granted non-qualified stock options to purchase an aggregate of 235,700 shares of the Company’s common stock (“Stock Options”) and an aggregate of 33,450 restricted stock units of the Company’s common stock (“RSUs”) to newly hired employees of the Company as an inducement material to such employees’ entry into employment with the Company, in accordance with Nasdaq Listing Rule 5635(c)(4) (the “Inducement Grant”).

The Stock Options have a ten-year term and an exercise price per share of $23.23, which is equal to the closing price of Zenas’ common stock on the Grant Date. The Stock Options will vest over a four-year period, with 25% of the shares vesting on the one-year anniversary of each of the employees’ first day of employment with the Company, and thereafter the remainder of the option will vest in 36 equal monthly installments. The RSUs will vest in four (4) equal installments over a four-year period, with vesting as to twenty-five percent (25%) of the RSUs subject to the award on each of March 15, 2027, March 15, 2028 March 15, 2029 and March 15, 2030. Inducement Grants are subject to the employees’ continued service with Zenas through the applicable vesting dates. The Inducement Grants were granted pursuant to, and are subject to, the terms and conditions of the Company’s 2026 Inducement Plan and the applicable award agreement.

About Zenas BioPharma, Inc.

Zenas is a clinical-stage global biopharmaceutical company committed to becoming a leader in the development and commercialization of transformative therapies for patients living with autoimmune diseases. Our core business strategy combines our experienced leadership team with a disciplined product candidate acquisition approach to identify, acquire and develop product candidates globally that we believe can provide superior clinical benefits to patients living with autoimmune diseases. Zenas is advancing two late-stage, potential franchise molecules, obexelimab and orelabrutinib. Obexelimab, Zenas’ lead product candidate, is a bifunctional monoclonal antibody designed to bind both CD19 and FcγRIIb, which are broadly present across B cell lineage, to inhibit the activity of cells that are implicated in many autoimmune diseases without depleting them. We believe that obexelimab’s unique mechanism of action and self-administered, subcutaneous injection regimen may broadly and effectively address the pathogenic role of B cell lineage in chronic autoimmune disease. Orelabrutinib is a potentially best-in-class, highly selective CNS-penetrant, oral, small molecule BTK inhibitor. Orelabrutinib’s mechanism of action targets pathogenic B cells not only in the periphery but also within the CNS. Additionally, it directly modulates macrophages and microglial cells in the CNS, with the potential to address compartmentalized inflammation and disease progression in MS. Zenas’ earlier stage programs include ZB021, a preclinical, potentially best-in-class, oral, IL-17AA/AF inhibitor, and ZB022, a preclinical, potentially best-in-class, oral, brain-penetrant, TYK2 inhibitor. For more information about Zenas BioPharma, please visit https://zenasbio.com/ and follow us on LinkedIn.

The Zenas BioPharma word mark, logo mark, and the “lightning bolt” design are trademarks of Zenas BioPharma, Inc. or its affiliated companies. All rights reserved.

Investor and Media Contact:

Argot Partners
Zenas@argotpartners.com